
The intersection of federal housing policy and immigration status serves as a key indicator of economic opportunity in the United States. For Deferred Action for Childhood Arrivals (DACA) recipients and non-permanent resident visa holders, obtaining a mortgage represents far more than a financial transaction—it is a foundation for long-term stability and generational wealth.
However, regulatory decisions by the Federal Housing Administration (FHA) under the U.S. Department of Housing and Urban Development (HUD) demonstrate how administrative pivots can instantly re-shape credit accessibility. Examining these policy mechanics, strategic buyer workarounds, and housing market trends is essential for real estate professionals, mortgage originators, and prospective home buyers navigating this landscape.
1. Policy Analysis: The Changing Federal Stance
The Expansion Era (2021–2025)
For years, ambiguous wording in the HUD Single Family Housing Policy Handbook (Handbook 4000.1) created conflicting underwriting rules regarding whether DACA holders qualified for government-insured loans.
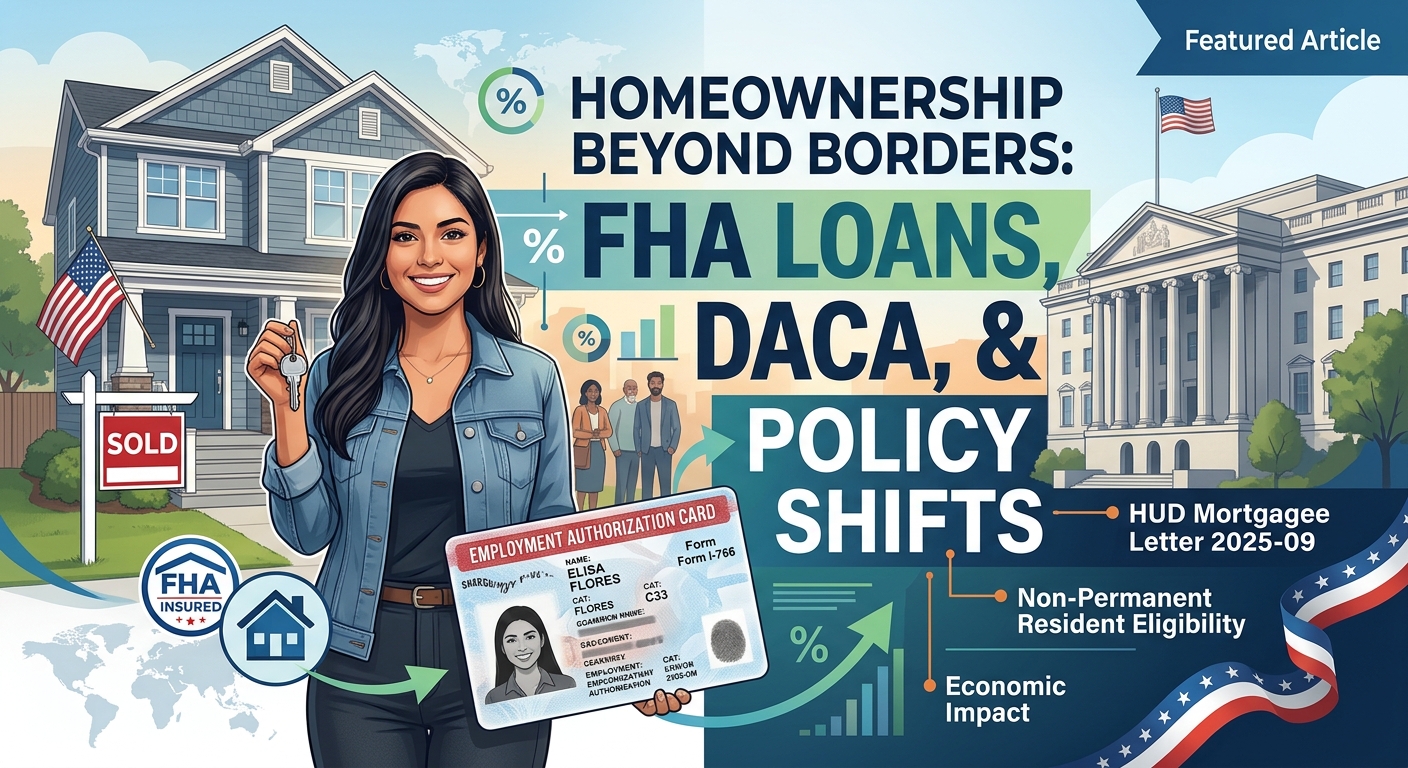
In January 2021, HUD clarified its stance by declaring that DACA recipients with a valid Employment Authorization Document (EAD / Form I-766) and a Social Security Number (SSN) were eligible for FHA financing under standard non-permanent resident terms. This decision provided access to low-down-payment options (as low as 3.5%) and flexible credit criteria.
The Policy Pivot (Mortgagee Letter 2025-09)
The federal framework reversed significantly following the issuance of HUD Mortgagee Letter 2025-09. Taking effect for FHA case numbers assigned on or after May 25, 2025, HUD removed non-permanent resident status entirely from FHA Title II loan eligibility. This eliminated FHA access for DACA recipients, H-1B, L-1, TN visa holders, and asylum applicants.
Under current regulations, FHA loan eligibility is strictly restricted to:
- U.S. Citizens
- Lawful Permanent Residents (Green Card Holders)
- Citizens of the Compacts of Free Association (COFA) states (Micronesia, Palau, Marshall Islands)
                        HUD MORTGAGE ELIGIBILITY TIMELINE

  Pre-2021               Jan 2021 – May 2025               May 25, 2025 Onward
  Ambiguous Policy   --->  DACA / EAD Eligible       --->  FHA Restricted to Citizens &
  (Lender Variance)      (3.5% Down FHA Loans)             Permanent Residents (Green Cards)
The Legal and Economic Rationale
HUD cited risk mitigation within the Mutual Mortgage Insurance (MMI) fund, stating that immigration status shifts or work permit expirations pose default risks. Conversely, policy analysts note that excluding tax-paying non-citizens—who demonstrate high labor participation and low default rates—illustrates how housing credit criteria are frequently influenced by broader federal immigration priorities.
2. Market Trends: Shifting Demand to Private Credit Channels
The exclusion of non-permanent residents from government-backed loans produced immediate ripple effects across the residential mortgage market.
| Market Metric | Pre-Policy Shift | Post-Policy Shift | Primary Impact |
| FHA Non-Resident Share | ~3.8% of FHA origination volume | Near 0% | Complete restriction of non-permanent buyers in FHA channels. |
| Primary Markets Impacted | TX, NY, FL, CA, WA | Major Metros (NYC, Houston, Dallas, Miami) | Immigrant tech and healthcare professionals redirected to conventional loans. |
| Housing & Rental Demand | Gradual tenant-to-owner path | Extended rental tenure | Higher down payment hurdles slow home purchases, keeping rental occupancy high. |
Regional Market Adjustments
Metropolitan areas with heavy concentrations of international professionals and first-generation residents saw a rapid transition away from government channels. Because non-resident buyers represent a substantial portion of entry-level housing purchasers, restricting government credit shifts overall demand directly toward private secondary market buyers.
3. Buyer Advice: Pathways to Homeownership Outside FHA
While FHA loans are restricted for non-permanent residents, several viable home financing pathways remain available.
                 ALTERNATIVE MORTGAGE PATHWAYS FOR NON-PERMANENT RESIDENTS

       ┌───────────────────────────────┼──────────────────────────────┐
       │                               │                              │
       ▼                               ▼                              ▼
  CONVENTIONAL LOANS             ITIN FINANCING               PORTFOLIO / NON-QM
(Fannie Mae / Freddie Mac)    (Non-SSN Tax ID Holders)     (Alternative Documentation)
 • 3%–5% Down Payment          • 10%–20% Down Payment       • Flexible Income Verification
 • Valid EAD / Visa Required   • Higher Interest Rates      • Higher Down Payment Required
1. Conventional Mortgages (Fannie Mae & Freddie Mac)
Unlike FHA guidelines, government-sponsored entities (GSEs) like Fannie Mae and Freddie Mac permit non-permanent resident financing.
- Eligibility: Borrowers with a valid Social Security Number and an unexpired Employment Authorization Document (EAD Form I-766, including Category C33 for DACA) can qualify for conventional financing.
- Down Payment: First-time buyers can access down payments as low as 3% to 5%.
- Underwriting: Requires a 2-year U.S. employment history, consistent income documentation (W-2s, tax returns), and evidence that work permit status is current.
2. ITIN Loan Programs
For non-citizens without a Social Security Number who file federal income taxes using an Individual Taxpayer Identification Number, specialized lenders offer dedicated ITIN Home Loans.
- Requirements: Typically require a 10% to 20% down payment, proof of two years of tax filings, and verified employment or non-traditional credit references (e.g., utility and rent payment histories).
3. Non-QM & Portfolio Lending
Credit unions and portfolio lenders retain mortgages on their own balance sheets rather than selling them to secondary market investors.
- Benefits: These institutions maintain custom underwriting flexibility, accommodating visa renewals, foreign asset validation, or alternative income structures.
Action Plan for Non-Permanent Resident Homebuyers
- Maintain Valid Work Documentation: Ensure your EAD card (Form I-766) or visa status (H-1B, L-1, TN) remains active, with documented renewal filings prepared well before expiration dates.
- Select Non-Permanent Resident Experienced Originators: Partner with mortgage brokers familiar with Fannie Mae Non-Citizen Guidelines rather than FHA-focused lenders.
- Optimize Credit Profiles: Conventional loans enforce stricter credit scoring than FHA programs. Maintaining a credit score of 620+ (ideally 700+) helps secure lower interest rates and reduced private mortgage insurance (PMI) premiums.
- Leverage Local Down Payment Assistance (DPA): Research state housing finance agency (HFA) programs, many of which allow work-authorized non-permanent residents to combine DPA grants with conventional mortgages.
Key Takeaway
Federal housing policy for non-permanent residents continues to evolve. While HUD’s regulatory changes removed FHA financing for DACA recipients and visa holders, conventional channels through Fannie Mae and Freddie Mac—alongside private portfolio programs—continue to provide structured routes to property ownership. Thorough documentation, strategic credit management, and working with informed lending professionals remain essential to navigating the current market.
Watching a practical video guide can provide additional clarity on navigating documentation and lender rules.
DACA Mortgage Loans – DACA recipients can buy a home
DACA…FHA is not an option! But there is hope….
Disclaimer: The content provided in this article is for informational, educational, and analytical purposes only and does not constitute formal legal, tax, or financial advice. We, Heru Vision are strategic brand and business management consultants, not attorneys or licensed mortgage originators. Housing regulations and lending policies fluctuate rapidly; readers should consult with a qualified legal professional or licensed mortgage advisor regarding their specific legal status and financial options.
